Your house flooded. Maybe the Trinity came up slowly over two days. Or a creek behind the fence went from ankle deep to knee deep in twenty minutes. Maybe a supply line let go and turned your garage into a shallow pool. Whatever happened, you’re holding a property that feels harder to sell than it actually is. Harder isn’t impossible, though, and you have more control here than the internet will admit.
What Options Do You Have When Selling a Flood-damaged Home in Texas?
Can a flooded house in Texas even be sold, or are you stuck holding a liability?
Selling is an option, and Texas hands you more flexibility than most states do. State law lets you sell a flooded house as-is, and plenty of buyers will take a home in its current condition. That one fact changes the math for homeowners who assume every repair has to happen before they can get out. It doesn’t. You don’t have to fix a thing first.
The real question isn’t whether a sale is possible. It’s which route fits your situation. You can repair the house and list it on the open market. You can sell as-is to a traditional buyer who wants a project. Or you can sell straight to a cash buyer who prices the damage in up front and closes without the usual drama. Each route carries its own timeline, its own cost, and its own kind of buyer waiting at the other end.
Family dynamics stacked on top of property damage make the choice harder. Early last year I helped three siblings sort out an inherited house in Mesquite, just east of Dallas, a three-bedroom place that had sat empty for months after the estate settled. Thirty years of belongings filled every closet. The garage still held furniture from the 1990s. Two of them wanted to list it. One just wanted a check. The house had taken on water more than once, and in my experience that’s the detail that finally breaks a family’s patience for drawn-out negotiations. We closed on a Thursday. They split the proceeds, and nobody had to argue about the garage.
The lesson isn’t sentimental. It’s arithmetic. Agreeing on one path early saves money in carrying costs, and it saves relationships too. While those three debated, the property sat for months, racking up taxes, insurance, and a slow-developing mold problem.
Texas has plenty of flood-prone geography, and Dallas-Fort Worth holds its share. FEMA’s flood maps cover this whole state, so nobody here gets to feel exempt. Look at the creek corridors threading through Fort Worth, the low ground along the Trinity in Dallas County, the drainage basins around Arlington and Grand Prairie, the older low-lying pockets in Garland and Irving. Flood damage is a regional reality, not a problem that stays down in San Antonio.
Most sellers who reach us have already been through the insurance process. Many are frustrated by what the payout covered versus what the repairs actually cost. Building claims pay full replacement cost only when the home is your primary residence and insured to at least 80 percent of replacement cost. Otherwise the claim pays depreciated actual cash value, which on an older house can fall well short of the repair bill. The gap between the insurance check and the real cost of getting a house market-ready is where sellers get stuck. I’ve watched that gap derail sales that looked straightforward on paper.
Knowing your options cold, before you sign anything, is worth more than any single repair you could make.
What Are the Challenges of Selling a Water-damaged House in Texas?
Over 38,600 homes across nine counties were likely damaged during the Central Texas flash floods in the summer of 2025. Damage at that scale complicates the market around each affected area, and it happens fast. Inventory piles up. Buyer confidence thins out. Lenders pull back from properties with a troubled record, because flood history follows a title.
Water damage creates cascading problems that don’t announce themselves. A buyer walking through a repaired house isn’t wrong to worry, since they’ve read the same headlines you have. Mold can develop behind walls within 48 hours of flooding, so a house that looked clean after the mucking out may hide a problem the next inspector finds. Foundations shift. Subflooring buckles. Electrical systems that sat underwater can pass a visual inspection and still fail a load test.
Financing is another wall. Conventional lenders aren’t enthusiastic about flood-damaged property. If the local floodplain administrator has tagged the home substantially damaged, meaning repair costs hit 50 percent or more of pre-damage market value, the rules tighten further. Federal floodplain rules require the whole building be brought into compliance with current flood-resistant construction standards. You’re not just fixing what broke. You’re rebuilding to a stricter standard than the one the house was originally permitted under. That can mean elevating the structure, not patching drywall.
The average annual cost of home insurance in Texas has reached $4,585, which is 117 percent more than the national average of $2,110, according to NerdWallet. That figure matters because it shapes what a buyer will pay. Buyers price in their ongoing cost of ownership, and a flood-zone property with high insurance premiums and a documented damage history costs more to own than a comparable house on higher ground. The difference lands in the offer price. It’s usually not a small adjustment.
Sellers also have to reckon with a market less forgiving than it was two or three years ago. In June 2026, homes in Texas sold at a median price of $347,911, and median days on market had reached 69 days, up three days year over year. A flood-damaged home listed on the open market will almost always sit longer than that median. Longer days on market mean more carrying costs for you and more leverage for the buyer, and every extra week costs real money.
None of this is meant to discourage you. It’s meant to hand you an honest picture, so your pricing and your plan match what buyers will actually do.
How Does Water Damage Impact Property Value?
For years I assumed the main value problem with a flood-damaged home was the visible damage. Wrong. The bigger hit is the history itself.
Even after full remediation, a professionally repaired foundation, new drywall, new flooring, and fresh paint, the flood record follows the house. It sits in the disclosure. FEMA keeps its own copy. Any future buyer who checks the property’s history will find it. Real estate professionals who specialize in water-damaged properties consistently see price reductions of 20 to 30 percent against similar homes with no flood history, and that’s with the repairs finished, sometimes years after closing.
That’s not a negotiating position. That’s the market, and the buyers in it, telling you how firmly flood history sticks. The discount holds anyway.
Location matters too. A home inside a mapped Special Flood Hazard Area carries a different stigma than one that took water once in a once-in-a-generation storm and sits on high ground. Buyers and their lenders treat those two situations very differently. Once a home falls inside a floodplain, the value drops, and a new assessment is needed to measure the impact against the specific risk zone classification. A high-risk FEMA flood zone designation on your property narrows the buyer pool to cash buyers, or to buyers willing to carry expensive flood insurance through the National Flood Insurance Program.
Years after a flood event, sellers who want out discover the disclosure demands the full flood history, and retail buyers keep walking. That isn’t pessimism. The pattern repeats across Dallas County, in the creek-corridor properties around Grand Prairie and Mesquite, in the older subdivisions in Garland built before current drainage standards. The disclosure is permanent. History doesn’t fade.
Appraisers handle flood-damaged properties differently depending on whether the repairs were permitted. Unpermitted work compounds the problem. The damage sits in the property’s history while the fix isn’t verifiable, which leaves the appraiser unable to give you credit for it. The buyer’s inspector will flag it anyway. Sellers who cut corners on flood remediation to save money usually end up with a property that’s harder to price and harder to close.
The most honest framing goes like this. Your floor on value isn’t the land value, and it isn’t what the house was worth before the water came in either. The real number sits between those two, shaped by which repairs got done, how they were documented, and where the property lands on FEMA’s flood maps.
What Are Your Legal Disclosure Obligations When Selling a Flood-damaged Home in Texas?
Skip the disclosure requirements on a flood-damaged Texas home and you’re risking more than a collapsed sale. You’re looking at liability under the Texas Deceptive Trade Practices Act, with damages that can reach up to three times actual losses. Get this part wrong and the consequence follows you. It doesn’t end at closing.
In Texas, sellers of single-unit residential properties must give buyers a Seller’s Disclosure Notice under Texas Property Code Section 5.008. The form covers a long list of property conditions, and flood history sits near the top. Your listing agent or broker isn’t responsible for filling it out. You are. The form reflects your personal knowledge, not their professional assessment.
After Hurricane Harvey, Texas tightened its flood disclosure requirements. Sellers now have to name the property’s FEMA flood zone designation, both 100-year and 500-year floodplains. They also disclose previous flooding from a reservoir breach, water penetration from natural flood events, flood insurance claims filed, and any FEMA or SBA assistance received.
One newer addition deserves attention. As of January 2025, the updated TREC Seller’s Disclosure Notice asks sellers to state whether mold remediation happened on the property within the past five years. If you had mold treated after a flood and figured it wouldn’t need disclosing, that’s no longer true. The form asks you directly now.
You must disclose flooding even if it happened before you owned the home, as long as you’re aware of it. So if a neighbor mentioned the house flooded in an earlier storm, or you found evidence of prior water damage when you moved in, those are disclosable facts. “I didn’t technically know” is a harder defense than it sounds when the evidence is visible.
An as-is clause in a Texas real estate contract means the buyer accepts the property in its current condition without requiring repairs. That clause doesn’t erase the seller’s disclosure obligations under Texas Property Code Section 5.008, though, and a seller who actively conceals a material defect stays liable even with an as-is clause in place.
The TREC Seller’s Disclosure Notice is free on the Texas Real Estate Commission website, in their forms library. Get it, read every section, and answer honestly. If you’re genuinely uncertain about something, “Unknown” is an acceptable answer when it’s true. Using it as a strategy to dodge something you know about is another matter entirely.
Is Repairing Water Damage Necessary Before You Sell?
A seller in Waxahachie called me last spring after a contractor priced the full restoration of her flooded ranch house. The number was $68,000. Her insurance payout covered about half of it. What she wanted to know was whether spending her own money on the gap would come back to her in the sale price.
It didn’t add up. The property carried a flood history no matter what she spent, and neighborhood comps for repaired flood-damaged homes weren’t telling a story where she’d recover that investment dollar for dollar. She sold as-is.
That’s not a universal answer. Sometimes repairing damage is the right move, especially when the damage is cosmetic and the cost is modest against the price bump a clean inspection delivers. The common advice to fix it all before you list, though, ignores something basic. Repair money on a flood-damaged property doesn’t return the way it does on a house with a clean history. Texas buyers discount flood history even when everything looks perfect. They know what they’re looking at, and so do their lenders.
The math that matters is simple enough. What does full remediation cost? What do repaired comparable sales actually show? And what’s the realistic spread in what buyers will pay? If the gap between repaired and as-is value on that property is narrower than the repair cost, selling as-is is arithmetic, not surrender.
Sellers routinely underestimate the timeline cost of repairs. Permitted work on a flood-damaged home can take months to finish and inspect. Every week the house sits under renovation is another week of mortgage payments, property taxes, utilities, and homeowner’s insurance, and permits alone can stall things badly. Those carrying costs eat straight into whatever margin the repairs were supposed to create.
Unlike a standard homeowner’s policy that covers additional living expenses after a covered loss, NFIP pays nothing toward those costs. Every month in a rental while the house sits gutted comes out of your pocket. That’s a real number, and it belongs in your repair-versus-sell calculation.
Which Repairs Give You the Best Return on a Flood-damaged Home?
A property in Rockwall came through with a finished floor plan after a buyer’s inspector found mold behind the kitchen baseboards that the earlier remediation had missed. The sale collapsed on a Tuesday. Four weeks and a proper mold abatement later, the seller relisted and closed without incident.
Mold is the repair that earns its money. A documented, permitted mold remediation with a clearance certificate from a licensed Texas mold assessor gives buyers and their lenders something concrete to point at. Without it, every inspector who walks that house flags the same concern, and you pay for the remediation anyway through buyer credits or collapsed sales. Our guide on selling a house with mold in Texas digs deeper into that piece.
Structural problems come second. If the foundation shifted, if load-bearing walls show cracking, or if the subflooring is compromised, none of that stays hidden past a professional inspection. Permitted work and documentation won’t erase flood history from a buyer’s mind, but they do remove the hard objection that kills sales. Our page on selling a house with foundation issues in Texas covers the repair side in detail.
Roofs take damage independently of flooding, though flooding often hits them too, whether through storm surge, debris, or the weight of pooled water. A roof documented as inspected and in good condition is one less thing for the buyer’s inspector to use as leverage in negotiations.
What doesn’t earn much back on a flood-damaged home: cosmetic upgrades. New countertops, appliance packages, and fresh paint don’t move the needle enough on a property with flood history to justify the cost. A buyer already processing the flood disclosure will not pay a premium for granite. Address the safety items and document the work. The luxury finish-out can wait for the next owner.
Working with Southern Hills Home Buyers is worth a look if the repair math keeps coming up short. They’ll give you a clear read on what the property is worth as-is and let you decide from there, with no pressure to fix anything first.
What Can You Do to Improve Curb Appeal After Water Damage?
A flood-damaged house still needs a strong first impression, maybe more than a clean one does. Buyers decide in the driveway.
Any buyer who pulls up to a neglected exterior is braced for bad news before they ever reach the disclosure form. Exterior condition signals how the rest of the property was cared for. If the yard is overgrown, the fence still leans where the water pushed it, and the front door shows staining, that buyer’s first instinct is to cut the offer.
Cleanup and basic landscaping cost almost nothing against what they return in buyer confidence. Mowing and edging the yard, clearing debris, power washing the driveway, resetting displaced fencing: a weekend and a few hundred dollars. That isn’t renovation. That’s showing respect for your own property.
For homes where flooding visibly damaged the exterior, spend money on what a buyer sees from the street. Fresh exterior paint on the lower third of the house, new address numbers, cleared gutters, a cleaned-up driveway: all of it says the property was attended to after the event. Waterline staining is the thing buyers photograph first. None of this fixes the property’s flood history, but it stops the exterior from amplifying it.
One mistake sellers make over and over is leaving dead landscaping in place after a flood. If the plants didn’t survive the flooding, pull them. Dead vegetation in front of a flood-damaged house tells a buyer a story that undercuts every repair you made inside. Bare dirt with a fresh layer of mulch beats a graveyard of ornamental bushes.
Don’t stage the inside before you handle the outside. A beautifully staged interior that a buyer reaches by walking past a damaged, neglected exterior creates a whiplash effect, and whiplash breaks trust. Get the outside presentable before anyone reads the flood disclosure.
Who Buys Water-damaged Homes in Texas and How Do You Find Them?
Most sellers expect their listing agent to put the house on the MLS, buyers to show up, and someone to make an offer. On a flood-damaged property that sequence breaks down at several points before it ever reaches an offer.
Retail buyers who finance have a lender standing between them and the closing table. Lenders scrutinize flood history. A property in a FEMA-designated Special Flood Hazard Area requires federally mandated flood insurance for any buyer using a government-backed loan. Participation in the NFIP rests on a community’s agreement to adopt and enforce federal standards for building inside a Special Flood Hazard Area. That insurance requirement is a carrying cost buyers fold into their offers, and it narrows who can qualify for what.
Buyers capable of absorbing flood-damaged properties fall into a few categories. Experienced investors and rehabbers make a business of distressed property. Builders see land value and don’t much care about the structure. Cash buyers evaluate the risk themselves, without a lender’s criteria standing in the way.
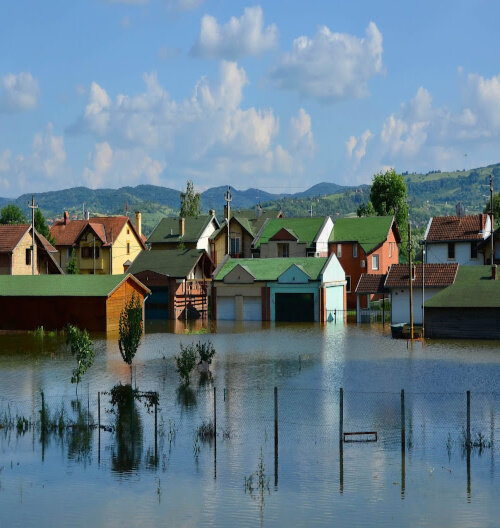
Finding those buyers through a traditional listing works sometimes, though you’re competing for their attention against every other distressed property on the market. The number of homes for sale in Texas increased statewide by 23.1% in 2025, which gives buyers who hunt distressed property more choices and more leverage than they had two years ago.
Real estate investors who specialize in flood-damaged homes are the more direct route. They’ve already priced flood risk. They don’t need a clean inspection to move forward, and they won’t walk away because an appraiser gets nervous about the FEMA map. Southern Hills Home Buyers works exactly this way, making direct offers on flood-damaged homes for sellers in Plano, Denton, and the rest of the metro, no repairs, staging, or showings required.
A listing broker or realtor who handles distressed or as-is sales is worth a conversation if you want to test the open market first. Not every agent has priced and positioned a flood-damaged home. An agent who has never handled the disclosure requirements, or the buyer psychology around flood history, can hurt you more than help.
How Can Cash Buyers Help You Sell a Flood-damaged Home Fast?
Picking up where the buyer pool question left off: cash buyers remove the single biggest point of failure in a flood-damaged home sale, which is financing.
With no lender involved, there’s no appraisal contingency, no underwriting review, no lender-required repairs, and no chance the sale falls apart because an appraiser flagged the flood history. The offer is the sale. The timeline compresses from months to weeks. How Southern Hills Home Buyers buys homes takes about two minutes to read and shows exactly what that looks like.
Cash buyers also don’t flinch at the disclosure form. A buyer who has read a TREC Seller’s Disclosure Notice with yes checked next to flood history, mold remediation, and prior insurance claims has priced all of it before making an offer. That’s not charity. That’s how professional buyers in distressed-property markets operate. They accept a known risk in exchange for buying below retail. You accept a below-retail cash price in exchange for certainty and speed.
Speed carries a dollar value sellers often fail to count. Every month you hold a flood-damaged property costs money. There’s the mortgage payment if you still carry one, plus property taxes and utilities to keep the structure from deteriorating further. Then homeowner’s insurance on a house that’s harder to insure after a claim. Stack three or four months of that, and the lower cash offer starts looking a lot closer to the traditional route than it did on paper.
I worked with a landlord in Irving who had been trying to rent a property after it flooded. The tenants left after the first repair attempt. The second round of repairs didn’t hold. By the time he called me, the house had sat vacant for several months with a mortgage running the whole way. He was done chasing it. We walked the property on a Saturday, and he’d kept the garage tidy even though the main house needed serious work. We closed without him ever having to handle a buyer’s agent negotiating against him.
That’s the clearest illustration of what certainty is worth. He didn’t get top dollar. He got out clean, stopped the bleeding on carrying costs, and moved on. For him that was the right trade.
Southern Hills Home Buyers buys flood-damaged homes across Texas for cash, with no repairs required, no commissions, and no obligation to accept the offer you get.
Frequently Asked Questions
How Hard Is It to Sell a House in a Flood Zone?
Selling in a designated flood zone is genuinely harder than a standard sale, and it isn’t impossible. Your buyer pool shrinks, because anyone using a government-backed mortgage has to carry federally required flood insurance, which raises the carrying cost of ownership and shapes what they’ll pay. Cash buyers and investors are the most reliable path to a completed sale, since they judge the property on their own terms without a lender’s criteria in the way. Pricing the property’s flood zone designation into your list price from the start saves you the painful negotiation later.
Do You Have to Disclose Mold Remediation When Selling a House in Texas?
As of January 2025, the updated TREC Seller’s Disclosure Notice added a question about mold. Sellers state whether mold remediation occurred on the property within the past five years, with a yes or no answer and space to explain a yes. So if mold was treated after your flood, it goes on the form. Answering honestly protects you. Concealing it and having a buyer discover it later puts you in a much worse spot.
Do Realtors Have to Disclose Water Damage?
Texas requires sellers to disclose known material defects on the TREC Seller’s Disclosure Notice, and flooding history counts. The obligation sits with you as the seller, not exclusively with your agent, though your listing agent or broker carries their own duty not to misrepresent the property’s condition. A good listing agent walks you through each relevant section before the property goes on market. Omitting water damage you knew about exposes both you and your agent to liability after the sale. We’ve written about what happens when a seller didn’t disclose the damage, and none of it ends well for the seller.
How Long Are You Liable for a House After You Sell It?
Seller liability does not end at closing. Concealing a known defect exposes the seller to liability after closing, even under an as-is contract. The specific timeframe for pursuing claims varies with the type of claim involved, and your county’s court system or a Texas real estate attorney can give you specifics for your situation. For any flood-damaged property the takeaway is straightforward. A complete, honest disclosure at the time of sale is your best protection against anything coming back later.
Selling a flood-damaged home in Texas is a real decision with real money at stake. The right path depends on your timeline, your finances, and how much of the process you want to manage yourself. If you’d rather talk it through with someone who has bought hundreds of Texas homes in every condition, we’re here. No pressure, no obligation. We buy houses in Fort Worth and across the rest of Dallas-Fort Worth, along with flood-prone communities elsewhere in the state. Reach out to Southern Hills Home Buyers whenever you’re ready.
Get Cash For Your Texas House Today
We buy houses in Texas without the hassle and red tape. Get your no-obligation cash offer for your home and just be done. Selling in as-is condition has never been easier.